DSCR Loans in New Jersey
Buy or refinance a rental on the property’s rent, not your tax returns. No income documents, close in your LLC, up to 20 financed properties.
What is a DSCR loan?
A DSCR loan is a mortgage for investment property that is underwritten on the property instead of on you. DSCR stands for debt service coverage ratio: the property’s monthly rent divided by its full monthly payment. If the rent covers the payment, the loan works. Your W-2s, tax returns and personal debt-to-income ratio never enter the file.
That is why New Jersey investors reach for it. Self-employed buyers whose write-offs shrink their taxable income, portfolio landlords who have hit the ten-property conventional cap, and anyone who wants to hold title in an LLC all qualify on the same thing: does this rental pay for itself.
How the ratio is calculated
PITIA is the whole payment: principal, interest, taxes, insurance and association dues.
A 1.14 ratio means the rent exceeds the payment by 14%. That qualifies under most programs, which look for 1.0 to 1.25. At 1.0 the property breaks even; above it, it cash-flows.
DSCR loan requirements in New Jersey
Typical program guidelines. Exact terms depend on your credit, the property and the ratio, and your advisor confirms them before you commit to anything.
| Requirement | Typical guideline |
|---|---|
| Income documents | None. No tax returns, W-2s, pay stubs or employment verification. |
| Qualifies on | The property’s rental income divided by its full payment (PITIA). |
| Minimum DSCR | 1.0 qualifies; 1.25+ gets the best terms. Ratios down to 0.75 and a no-ratio DSCR option are available with more down. Loans under $150,000 need 1.15. |
| Credit score | 660 minimum. 700 for first-time investors and interest-only; 720+ for the highest loan-to-value. |
| Down payment | 20–25% typical. 20% is the floor and needs a 720 credit score and a ratio of 1.0 or better. Below a 1.0 ratio, expect more. |
| Gift funds | Allowed in certain scenarios. |
| Loan-to-value | Up to 80% for purchase and rate-and-term refinance; up to 75% for cash-out on the strongest files, and cash-out above 65% loan-to-value is capped at $750,000. 2–4 units and condos stop at 80%; a declining market takes 5% off. |
| Loan amounts | $100,000 to $3 million. |
| Reserves | 3 to 12 months of the full payment by loan size: 3 months up to $500,000, 6 months to $1.5 million, 12 months above that. Nothing extra for your other properties, and cash-out proceeds can count. |
| Terms | 15-, 30- and 40-year fixed and ARMs. Interest-only (10 years, then 20 or 30 amortizing) needs a 700 credit score and 75% loan-to-value or less. |
| Prepayment | Optional in many scenarios: taking a prepayment penalty lowers the rate and costs, but it is not always required. |
| Vesting | Your personal name or an LLC, corporation or trust. Entity loans carry a personal guaranty, and everyone on the entity’s title must be a borrower on the loan. |
| Properties financed | Up to 20 financed properties per borrower, and up to ten loans or $5 million with us. Each property stands on its own ratio. |
| Who can borrow | U.S. citizens, permanent residents, non-permanent residents (75% loan-to-value max), foreign nationals and ITIN holders. |
The fine print
Straight from our DSCR underwriting guidelines. Your advisor confirms what applies to your file.
The floor is a 0.75 ratio. A no-ratio option is available with restrictions, and loans under $150,000 need a 1.15 ratio.
Ten years interest-only, then 20 or 30 years amortizing. Needs a 700 credit score and 75% loan-to-value or less (70% when the ratio is between 0.75 and 0.99). Not available with the no-ratio option.
A personal guaranty is required on every entity loan, and everyone on the entity’s title must be a borrower on the loan.
Neither you, your LLC’s members nor any relative may live in the property, and room-by-room or boarder leases do not qualify. You sign a business-purpose and occupancy affidavit at closing, and cash-out proceeds must be used for business purposes.
2–4 unit properties and condos, warrantable or not, top out at 80% loan-to-value. Co-ops are not eligible. Rural properties qualify up to 20 acres. In a declining market the maximum loan-to-value drops by 5%.
Twelve months of verified housing history on your primary home and on the subject property. One 30-day late is allowed when the ratio is 0.75 or better; the no-ratio option needs a clean 12 months. A foreclosure, short sale or bankruptcy must be three or more years old. Borrowers without 12 months of housing history are not eligible.
The higher of your lease or the appraiser’s market rent, with market rent usable up to 120% of the lease. A vacant purchase uses market rent with no vacancy factor. A refinance needs a lease in place, with exceptions for short-term rentals, recently rehabbed homes, delayed financing and 2–4 unit properties with one vacant unit listed for rent.
Up to 75% loan-to-value, cash-out eligible.
What you can finance
Purchase, rate-and-term refinance or cash-out refinance on 1–4 unit, non-owner-occupied residential property anywhere in New Jersey.
Does not qualify: primary residences, owner-occupied second homes, buildings of five or more units, mixed-use with more than 25% commercial space, land, construction, and in most cases manufactured homes.
Short-term rentals qualify, with the summer counted.
Seasonal weekly rates in Point Pleasant, LBI or Margate can cover months of mortgage. DSCR programs that understand short-term income use a booking history or a market projection, not a twelve-month lease. Check your town’s short-term rental ordinance, then run the numbers.
DSCR vs. a conventional investment loan
Conventional is cheaper when your income documents well and you own fewer than ten properties. DSCR wins everywhere else.
| Feature | DSCR loan | Conventional |
|---|---|---|
| Income documents | None, property income only | Tax returns, W-2s, pay stubs |
| Qualifies on | Property cash flow (the ratio) | Your personal debt-to-income |
| Properties financed | Up to 20 | Ten maximum |
| Title in an LLC | Yes | Personal name only |
| Typical closing | About 30 days | 30–45 days |
| Rate | About 0.5–1.5% higher | Lowest available |
DSCR calculator
Price, rent and carrying costs in; ratio, payment and monthly cash flow out. Nothing is saved and no one calls you.
Estimates for illustration only — not a rate quote or commitment to lend. Taxes, insurance and program terms vary.
What is the most I can pay?
Start from the rent you expect and the ratio you want to hit. The calculator backs into the highest purchase price that still covers itself.
Estimates for illustration only — not a rate quote or commitment to lend. Taxes, insurance and program terms vary.
Am I a DSCR candidate?
Six quick questions. You get a read on where you stand and what would strengthen the file. Nothing is submitted.
Working for you
Worth discussing
A quick read, not an approval. Program guidelines vary and your advisor confirms what you qualify for.
Certainty protects your deal
A blown closing date or a rate that moves after the lock can wreck an investor’s numbers. These are the three things we are built around.
Your rate, locked and kept locked
When we lock, the number on your term sheet is the number at the closing table.
You can always reach your loan officer
Especially in the last week. Direct cell, direct email, a real person who knows your file.
We hit the closing date
In-house processing and underwriting, and no income file to chase. The appraisal sets the pace, not your paperwork.
A New Jersey lender since 1999
Headquartered in Ocean, NJ. We know the towns, the tax bills and the rent rolls because we live here.
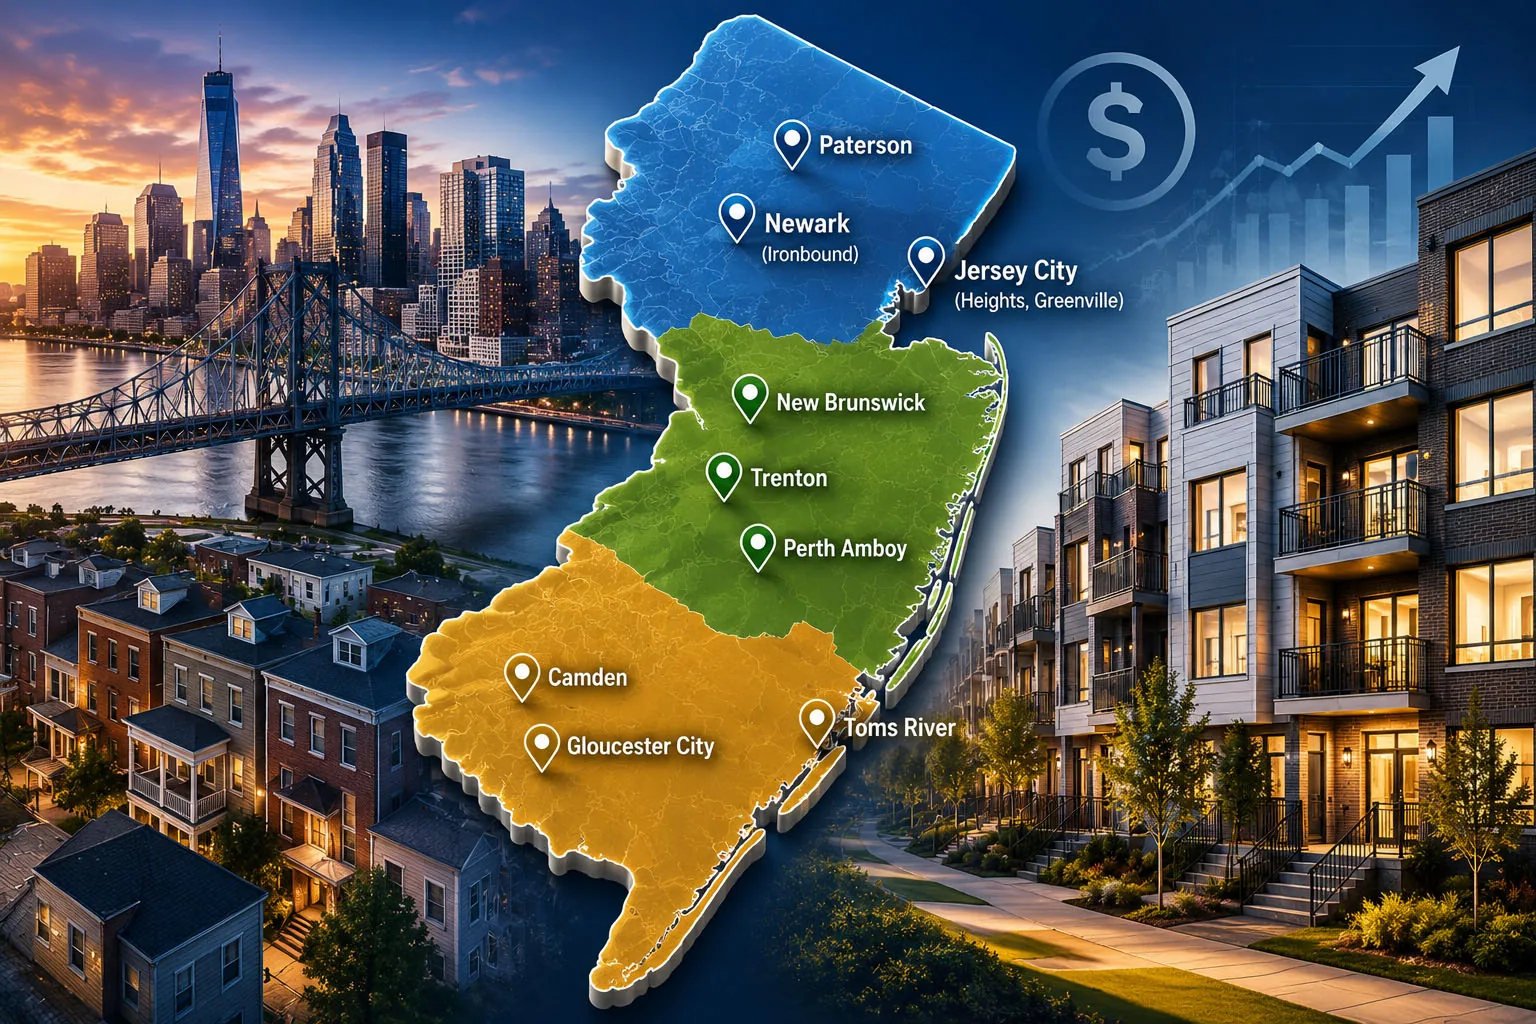
New Jersey rental markets at a glance
Location drives the ratio. Property taxes, achievable rent and entry price vary wildly across the state; a half-point of tax rate can move a borderline deal either way.
Ocean County
- Median sale price
- $477,500 Nov 2025
- 2-bedroom market rent
- $2,328/mo
- Effective tax rate
- 1.42%
Where investors buy: Toms River, Brick, Lakewood, Point Pleasant, Seaside Heights
Our home turf. Year-round demand inland, vacation-rental income at the beach, and one of the lower tax rates on this list.
Monmouth County
- Median sale price
- $745,000 May 2026
- 2-bedroom market rent
- $2,328/mo
- Effective tax rate
- 1.48%
Where investors buy: Asbury Park, Long Branch, Red Bank, Freehold, Middletown
Shore rentals plus NYC commuter demand. Higher entry prices; strong appreciation.
Bergen County
- Median sale price
- $755,000 Jan 2026
- 2-bedroom market rent
- $2,324/mo
- Effective tax rate
- 2.00%
Where investors buy: Hackensack, Fort Lee, Paramus, Englewood, Teaneck
Premium rents minutes from Manhattan. Tax rates swing widely by town (0.79% to 2.74%), which moves the ratio.
Middlesex County
- Median sale price
- $540,000 Nov 2025
- 2-bedroom market rent
- $2,486/mo
- Effective tax rate
- 1.82%
Where investors buy: New Brunswick, Edison, Perth Amboy, Woodbridge, Piscataway
Rutgers, the pharma corridor and the Route 1 employers keep the tenant pool deep.
Atlantic County
- Median sale price
- $390,000 Nov 2025
- 2-bedroom market rent
- $1,867/mo
- Effective tax rate
- 1.97%
Where investors buy: Atlantic City, Egg Harbor, Galloway, Hammonton, Margate
Lowest entry prices here, casino workforce year-round, vacation rentals at the beach.
Median sale price: Redfin county housing-market pages, month shown. Rent: HUD Fair Market Rent, 2-bedroom, FY2026. Tax: county average effective rate, SmartAsset / U.S. Census 2024. Figures change; your advisor runs current numbers for the property you are looking at.
Beyond these five: Newark, Paterson and East Orange for multi-family cash flow; Trenton and Camden for the lowest entry prices in the state; New Brunswick and Perth Amboy for deep tenant pools; Toms River, Brick and Point Pleasant for year-round plus summer income. We lend statewide.
DSCR loan questions, answered
A DSCR (Debt Service Coverage Ratio) loan is a mortgage for investment property that qualifies you on the rental income the property produces instead of your personal income. If the rent covers the mortgage payment (a DSCR of 1.0 or higher), you may qualify regardless of what your tax returns show.
No. DSCR loans do not require personal tax returns, W-2s, pay stubs or employment verification. Qualification is based on the property’s rental income compared with its monthly payment: principal, interest, taxes, insurance and any association dues.
A ratio of 1.0 or higher qualifies on standard terms, and 1.25 or better earns the best pricing. A 1.0 means the rent exactly covers the payment. We also lend down to a 0.75 ratio with more down, and a no-ratio DSCR option that skips the rent calculation is available with restrictions. Loans under $150,000 need a 1.15 ratio. Your advisor confirms the requirement for your scenario.
Typically 20–25% of the purchase price. 20% down is the floor, and it takes a 720 credit score and a ratio of 1.0 or better; 2–4 unit properties and condos also stop at 80% loan-to-value. Below a 1.0 ratio, expect more down. Gift funds are allowed in certain scenarios.
Yes. Closing in the name of an LLC or other entity is one of the main reasons investors choose DSCR loans. The LLC should be registered with the New Jersey Division of Revenue and you will need an operating agreement. Your advisor walks you through the entity paperwork.
Yes. DSCR loans can finance short-term and vacation rentals, including Long Beach Island, Point Pleasant and the Atlantic City area. For short-term rentals the income is usually taken from a rental history or a market projection. Check your town’s short-term rental ordinance before you buy.
Up to 20 financed properties per borrower, twice the conventional limit of ten, with a cap of ten loans or $5 million with us. Each property still has to cover its own payment.
Yes. Because the loan is underwritten on the property rather than on your personal income, DSCR programs are available to foreign national investors and ITIN holders buying New Jersey property. Expect to provide a passport, visa status and foreign credit references. Non-permanent residents top out at 75% loan-to-value and can take cash out.
1–4 unit residential investment property anywhere in New Jersey: single-family rentals, duplexes, triplexes, fourplexes, condos and townhouses, including non-warrantable condos. 2–4 unit properties and condos top out at 80% loan-to-value, and rural properties qualify up to 20 acres. The property must be non-owner-occupied. Primary residences, second homes, 5+ unit buildings, co-ops, land and construction do not qualify.
There is no income file to assemble, so the timeline is driven by the appraisal and rent analysis rather than paperwork. Most DSCR loans close in about 30 days; your advisor gives you a date once the appraisal is ordered.
Investor reading
Longer answers from the Knowledge Base.
Run your deal past Greg.
Send the address, the rent and the price. You get a straight answer on whether it qualifies and what the payment looks like, usually the same day.
Or call 609-992-5356 to reach Greg directly.
DSCR and Non-QM loans are arranged through third-party providers. Guidelines shown are typical program parameters and vary by program, property and borrower profile; your advisor confirms the terms for your scenario. This is not a commitment to lend. All loans subject to credit approval. Advisors Mortgage Group, LLC · NMLS #33041 · Equal Housing Opportunity.
Not sure if this program fits you? Ask — it is free.
A licensed local advisor compares your options and tells you what you qualify for. No obligation, no impact to your credit.